Edward Martin Edward Martin
0 Course Enrolled • 0 Course CompletedBiography
Latest AICPA FAR Test Objectives, FAR Latest Exam Labs
The top features of Exams4sures FAR exam questions are the availability of AICPA certification exam in three different formats, real, valid, and updated FAR exam questions, subject matter experts verified FAR Exam Questions, free demo download facility, 1 year updated FAR exam questions download facility, affordable price and 100 percent AICPA FAR exam passing money back guarantee.
Every person in IT industry should not just complacent with own life. Now the competitive pressures in various industries are self-evident, and the IT industry is no exception. So if you have a goal, then come true it courageously. Pass the AICPA FAR Exam is a competition. If you passed the exam, then you will have a brighter future. Exams4sures can provide you with the true and accurate training materials to help you pass the exam. And then you can achieve your ideal.
>> Latest AICPA FAR Test Objectives <<
FAR Latest Exam Labs, FAR Prepaway Dumps
The rapid development of information will not infringe on the learning value of our FAR study materials, because our customers will have the privilege to enjoy the free update for one year. You will receive the renewal of FAR study materials through the email. And our FAR study materials have three different version can meet your demands. Firstly, PDF version is easy to read and print. Secondly software version does not limit to the number of installed computers, and it simulates the Real FAR Exam environment, but it can only run on Windows operating system.
Introduction to Financial Accounting and Reporting (FAR) Exam
The Standardized CPA Evaluation is the exam portion of the Financial Accounting and Reporting (FAR) which measures the expertise and skills that a newly qualified CPA must demonstrate in the financial accounting and reporting systems used by enterprise (public and non-public), non-profit, and state and local government agencies.
In the FAR portion of the test, the examination contains the requirements and regulations provided by:
- U.S. Securities and Exchange Commission (U.S. SEC)
- Financial Accounting Standards Board (FASB)
- Governmental Accounting Standards Board (GASB)
- American Institute of Certified Public Accountants (AICPA)
- International Accounting Standards Board (IASB)
The FAR section consists of questions that emphasize the conceptual structure and financial reporting, the selection of accounts of financial statements, the selection of transactions, and the application of state and local governments to accounting work. These sections can be overviewed from the FAR practice test. References at the end of this introduction provide a list of guidelines and regulations provided by these bodies and other reference materials that are available for evaluation in the FAR portion of the review.
Financial Accounting and Reporting (FAR) Exam Certification Path
Generally, the more familiar you are with the FAR content, the less time you need to study, and the faster you can pass. So, how long will you need to study for FAR? Well, the best you can get is the FAR exam dumps that help you figure out what side of the study time spectrum you're probably on via a deeper investigation into FAR's content. You'll find the content areas, groups, and topics of FAR in the FAR CPA Exam blueprints.
Want to pass FAR fast? Then you'll need to study for 20 hours a week so you can finish your review in 6-8 weeks.
Can't fit that much study time into your routine? Then try studying for 15 hours a week. Doing so will prepare you in 8-11 weeks.
finally, if you can only study for 10 hours a week, you'll be ready for FAR in 12-16 weeks.
So, you can use any one of these study schedules or do anything in between. That's because of how fast you finish your FAR review depends on how much time you have to study in a week. But what's important is that you study consistently so you can stay in study mode and stick to your exam schedule.
AICPA CPA Financial Accounting and Reporting Sample Questions (Q128-Q133):
NEW QUESTION # 128
Which of the following should be disclosed in a summary of significant accounting policies?
- A. Composition of sales by segment.
- B. Future minimum lease payments in the aggregate and for each of the five succeeding fiscal years.
- C. Depreciation expense.
- D. Basis of profit recognition on long-term construction contracts.
Answer: D
Explanation:
Choice "a" is correct. The summary of significant accounting policies should disclose policies. The only
policy in this question is the "basis" of profit recognition on long-term construction contracts.
The other disclosures are accounting details and would be disclosed in other footnotes, but not in the
summary of significant accounting policies.
Choice "b" is incorrect. The future minimum lease payments should be disclosed, but not in the summary
of significant accounting policies.
Choice "c" is incorrect. Depreciation expense should certainly be disclosed, but not in the summary of
significant accounting policies.
Choice "d" is incorrect. The composition of sales by segment should be disclosed, but not in the summary
of significant accounting policies.
NEW QUESTION # 129
A development stage enterprise should use the same generally accepted accounting principles that apply
to established operating enterprises for: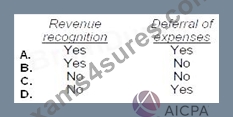
- A. Option C
- B. Option D
- C. Option A
- D. Option B
Answer: C
Explanation:
Choice "a" is correct. Development stage enterprises must use all the same principles as established
enterprises including those of revenue recognition and deferral of expenses. The primary difference is
that development stage enterprises must provide additional disclosures not required of established
operating enterprises. SFAS #7, para. 10
NEW QUESTION # 130
In April 30, 20X4, Deer Corp. approved a plan to dispose of a component of its business. For the period
January 1 through April 30, 20X4, the component had revenues of $500,000 and expenses of $800,000.
The assets of the component were sold on October 15, 20X4 at a loss. In its income statement for the
year ended December 31, 20X4, how should Deer report the component's operations from January 1 to
April 30, 20X4?
- A. $300,000 should be reported as part of the loss on disposal of a component and included as part of
continuing operations. - B. $300,000 should be reported as an extraordinary loss.
- C. $300,000 should be reported as a loss from operations of a component and included in loss from
discontinued operations. - D. $500,000 and $800,000 should be included with revenues and expenses, respectively, as part of
continuing operations.
Answer: C
Explanation:
Choice "d" is correct. Once the decision has been made to dispose of a component of a business and that
component meets the criteria to be classified as held for sale, the operating results of the component for
the period reported on, and any gain or loss from the disposal, should be reported separately from
continuing operations, net of tax. In this question, the component was classified as held for sale and was
sold in the same year.
Thus, in 20X4, the results of operations, the $300,000 ($500,000-$800,000) loss, are reported as a loss
from discontinued operations. The loss on disposal would be reported as part of that loss from
discontinued operations also.
Choice "a" is incorrect. The results of operations prior to the decision date, and also after the decision
date, are reported separately from the results of continuing operations as a part of discontinued
operations. Choice "b" is incorrect. The results of operations prior to the decision date, and also after the
decision date, are reported separately from the results of continuing operations as a loss from operations
of a component and included in loss from discontinued operations.
Choice "c" is incorrect. The results of discontinued operations are not reported as an extraordinary item.
NEW QUESTION # 131
Coffey Corp.'s trial balance of Income Statement Accounts for the year ended December 31, 1988 as
follows: Coffey's income tax rate is 30%. The gain on debt extinguishment is considered a usual and
recurring part of Coffey's operations. Coffey prepares a multiple-step income statement for 1988.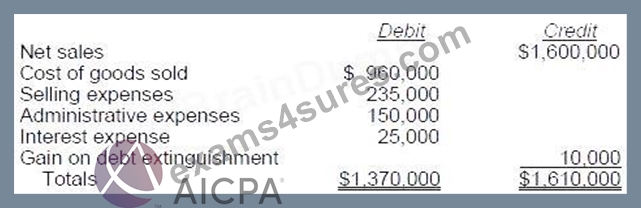
Income from operations before income tax is:
- A. $190,000
- B. $200,000
- C. $230,000
- D. $240,000
Answer: D
Explanation:
Choice "d" is correct. $240,000 The gain on debt extinguishment does not meet the unusual and
infrequent criteria of APB 30 to be treated as an extraordinary item (per SFAS No. 145, extinguishments
of debt are no longer automatically extraordinary), so it is included as part of income from continuing
operations.
NEW QUESTION # 132
According to the FASB conceptual framework, the process of reporting an item in the financial statements
of an entity is:
- A. Recognition.
- B. Matching.
- C. Realization.
- D. Allocation.
Answer: A
Explanation:
Choice "d" is correct. Recognition is the process of recording an item in the financial statements of an
entity. SFAC 5 para. 6 Choice "a" is incorrect. Allocation is the accounting process of assigning or
distributing an amount according to a plan or a formulA. SFAC 6 para. 142 Choice "b" is incorrect.
Matching of costs and revenues is simultaneous or combined recognition of the revenues and expenses
that result directly and jointly from the same transactions or other events. SFAC 6 para. 146 Choice "c" is
incorrect. Realization is the process of converting noncash resources and rights into money. SFAC 6 para.
1 43
NEW QUESTION # 133
......
If you want to constantly improve yourself and realize your value, if you are not satisfied with your current state of work, if you still spend a lot of time studying and waiting for FAR qualification examination, then you need our FAR material, which can help solve all of the above problems. I can guarantee that our study materials will be your best choice. Our FAR Study Materials have three different versions, including the PDF version, the software version and the online version.
FAR Latest Exam Labs: https://www.exams4sures.com/AICPA/FAR-practice-exam-dumps.html
- 2025 AICPA FAR: CPA Financial Accounting and Reporting High Hit-Rate Latest Test Objectives 🍂 Search for 《 FAR 》 on “ www.torrentvce.com ” immediately to obtain a free download 🐄FAR Practice Mock
- FAR High Passing Score 🛩 FAR Prepaway Dumps ☕ FAR Prepaway Dumps 🍻 Open ➡ www.pdfvce.com ️⬅️ and search for ▶ FAR ◀ to download exam materials for free 😒FAR New Exam Materials
- FAR High Passing Score 🅿 Valid Dumps FAR Book 💎 Online FAR Tests 🔚 Easily obtain 「 FAR 」 for free download through 【 www.testsdumps.com 】 🤽Valid Dumps FAR Book
- FAR Latest Mock Test 🐥 FAR New Exam Materials 🧦 FAR Unlimited Exam Practice 😦 Search on 《 www.pdfvce.com 》 for ▷ FAR ◁ to obtain exam materials for free download 🩺FAR Practice Mock
- Useful Latest FAR Test Objectives - Leader in Certification Exams Materials - First-Grade FAR Latest Exam Labs 🩺 Copy URL ☀ www.examcollectionpass.com ️☀️ open and search for ➠ FAR 🠰 to download for free 🧸FAR New Exam Materials
- FAR Latest Test Braindumps 🕧 FAR Pass Test 🔽 Exam Dumps FAR Free ⌚ Search for [ FAR ] and easily obtain a free download on ⏩ www.pdfvce.com ⏪ 🍤FAR Reliable Exam Pass4sure
- Exam Dumps FAR Free 🙆 FAR Free Practice 🕺 Reliable FAR Real Test 🦥 Open ⏩ www.getvalidtest.com ⏪ enter ☀ FAR ️☀️ and obtain a free download 🌔FAR Reliable Exam Pass4sure
- 2025 AICPA FAR: CPA Financial Accounting and Reporting High Hit-Rate Latest Test Objectives 🥦 Enter ✔ www.pdfvce.com ️✔️ and search for ✔ FAR ️✔️ to download for free 🏃FAR Free Practice
- 2025 AICPA FAR: CPA Financial Accounting and Reporting High Hit-Rate Latest Test Objectives 🔺 Open ▷ www.testkingpdf.com ◁ and search for “ FAR ” to download exam materials for free 🔂FAR Visual Cert Exam
- Useful Latest FAR Test Objectives - Leader in Certification Exams Materials - First-Grade FAR Latest Exam Labs 🚟 { www.pdfvce.com } is best website to obtain ⏩ FAR ⏪ for free download ◀FAR New Exam Materials
- 2025 AICPA FAR: CPA Financial Accounting and Reporting High Hit-Rate Latest Test Objectives 🍯 Search for “ FAR ” and obtain a free download on ➤ www.passtestking.com ⮘ 🤕FAR Exam Book
- FAR Exam Questions
- lms.icft.org.pk training.oraclis.co.za my.knowledgehub99.com learn.designoriel.com www.rumboverdadero.com jomacademyonline.com learnonline.sprintlearn.net ededcourses.com training.icmda.net iqedition.com
